A guide for Italian residents who want to check a used car in Spain, arrange its transfer and prepare properly for registration in Italy.
Importing a car from Spain can be worthwhile, but the decision should be based on the full cost and the practical possibility of registering the vehicle in Italy. Before paying a deposit, check three things: that the seller has the power to dispose of the car, that there are no Spanish restrictions incompatible with export, and that the technical and tax file is acceptable to your UMC or STA. Only then choose between collecting it for road use and carriage on a vehicle transporter.
This guide concerns a private individual already resident in Italy who buys an ordinary used M1 passenger car for personal use, already registered in mainland Spain. It does not cover a change of residence, historic or heavily modified vehicles, the Canary Islands, Ceuta or Melilla.
First decision: vehicle, seller and taxes
The word “used” in an advert is not enough for VAT purposes. In the EU, a vehicle is used for VAT purposes only if it has travelled more than 6,000 km and is supplied more than six months after first registration. It is new for VAT purposes if it has travelled no more than 6,000 km or is supplied within six months: one of the two conditions is enough. A car with exactly 6,000 km therefore does not fall within the definition of used for VAT purposes. 1 2
For an ordinary car used for VAT purposes, bought from a private seller in another EU State, transfer to Italy alone does not create new VAT on the car. If a trader sells it, you must instead read the invoice and the regime applied, distinguishing standard VAT and the margin scheme; a private buyer has no general right to a net price. On the ordinary intra-EU Spain–Italy route, there are no customs duties, but this conclusion must not be extended to special tax territories or non-EU purchases. 1 3
| Situation | Consequence | Practical action |
|---|---|---|
| More than 6,000 km and more than six months | Used for VAT purposes | Check the seller and invoice 1, 2 |
| No more than 6,000 km or within six months | New for VAT purposes | Clarify VAT before payment 1 |
| Private seller; non-resident buyer | National Form 620 may apply | Check the contract and taxable base 4 |
| VAT taxable seller | Form 620 branch excluded | Read the invoice and VAT regime 4, 1 |
If you buy from a private seller as a non-resident in Spain, the Form 620 described by the national AEAT may apply: the taxable person is the non-resident buyer. This page does not govern every Spanish sale: it excludes supplies made by VAT taxable persons and states that the national form is not the appropriate one for a buyer resident in Spain. In the applicable branch, the stated rate is 4%, the self-assessment must be made within 30 working days of the deed or contract, and the base is the higher of the actual value and the annual average sale price reduced for age, where the vehicle appears in the tables. The price written in the contract does not automatically become the taxable base. 4
Checks in Spain before payment
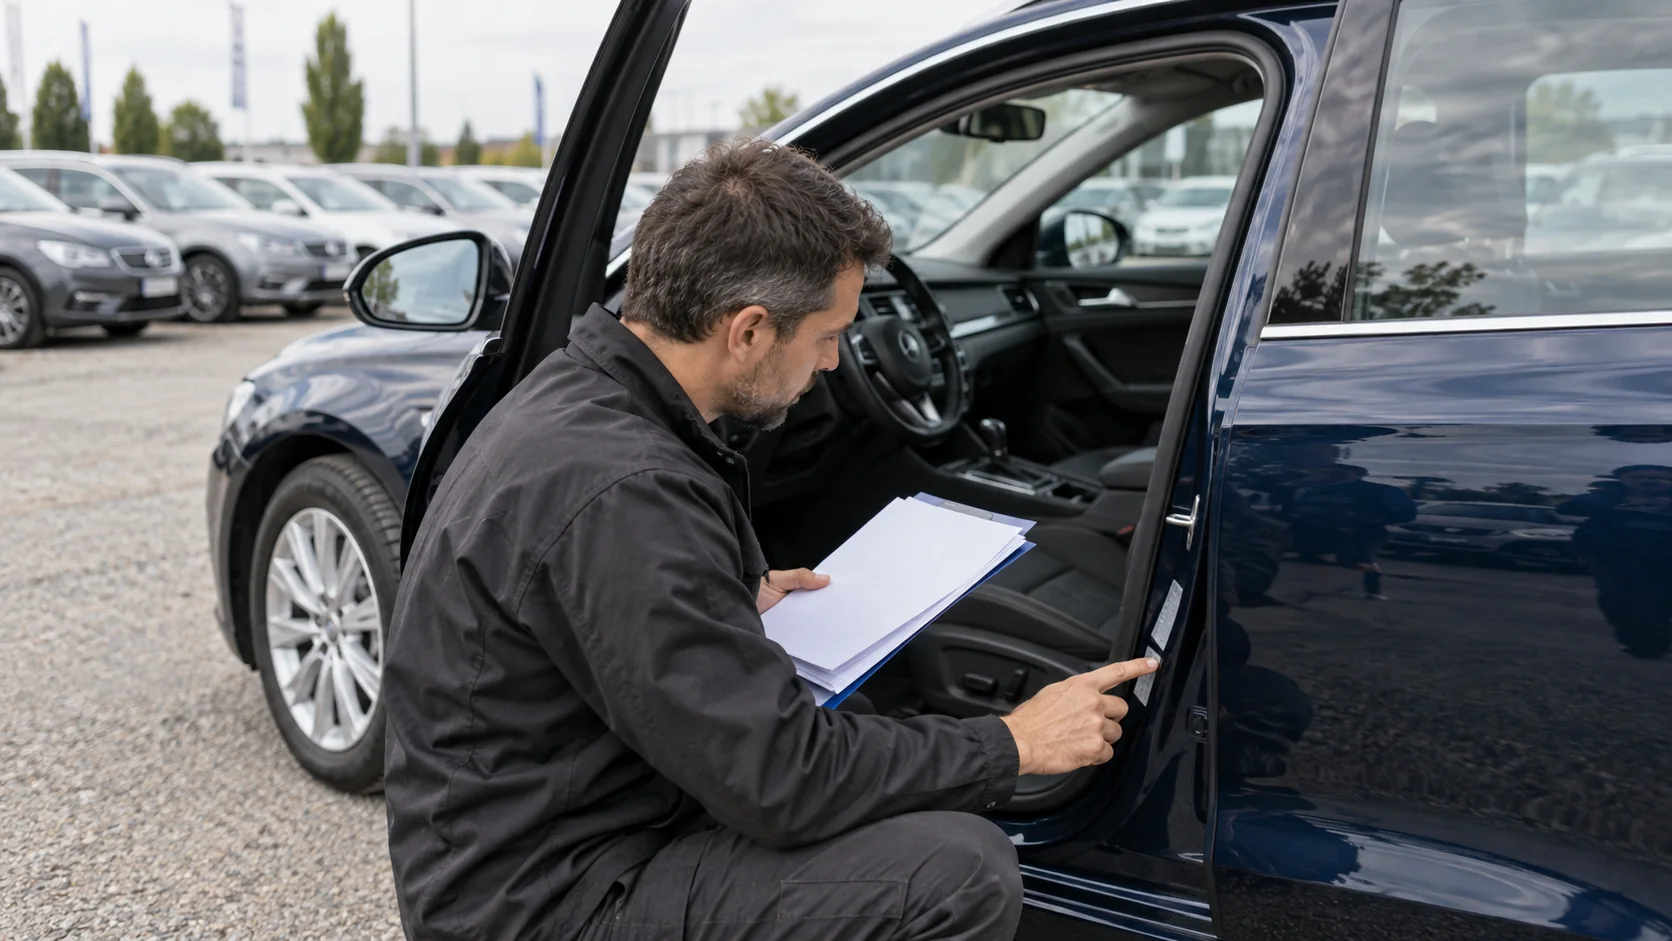
Ask for the VIN and compare it with the registration certificate, contract, invoices and vehicle plates. Identify the seller, establish the title to ownership and check that they have the power to sell. The free reduced DGT report offers limited information; for a pre-purchase check, DGT recommends the full report, which may show the registered holder, ITV, mileage, technical data, recalls, maintenance and encumbrances such as seizure, precinto, insolvency proceedings or other administrative and judicial restrictions. Even the full report alone does not prove the seller’s authority or the current physical condition. 5
Maintenance entries come from workshops participating in the DGT electronic register. The absence of an entry therefore does not prove that the car has not had repairs, accidents or odometer tampering. Compare the DGT history, invoices and mileage, then have the bodywork, underbody, diagnostics, cold start and road operation checked. 5
A precinto must be cancelled before definitive deregistration for export. A registered restriction on disposal must also be removed or expressly authorised by the finance company. The last paid instalment alone does not prove that a reserva de dominio has been cancelled from the register. Set out in the contract what happens if the seller cannot release the vehicle or provide the originals. 6
Documents to secure before buying
Before making a non-refundable payment, submit the composition of the file to your UMC or STA: this is a practical precaution, not a statutory deadline. The basis includes the title of purchase, identity and tax code, the complete original foreign registration document, both parts where the State issues them, technical data, the relevant tax and insurance evidence, and any technical-control documents. Damage, modifications or missing documents can change the route. 3 2 7
For a vehicle already registered in the EU, a non-harmonised registration certificate or one with additional annotations requires the relevant full translation. The COC may be submitted in the original or as a copy and does not require translation; however, it is not the only possible solution. Depending on the case, a translated supplementary technical sheet or other permitted technical evidence may be needed. Ask the competent office which alternative it accepts for that specific VIN. 3
Definitive deregistration and transport to Italy
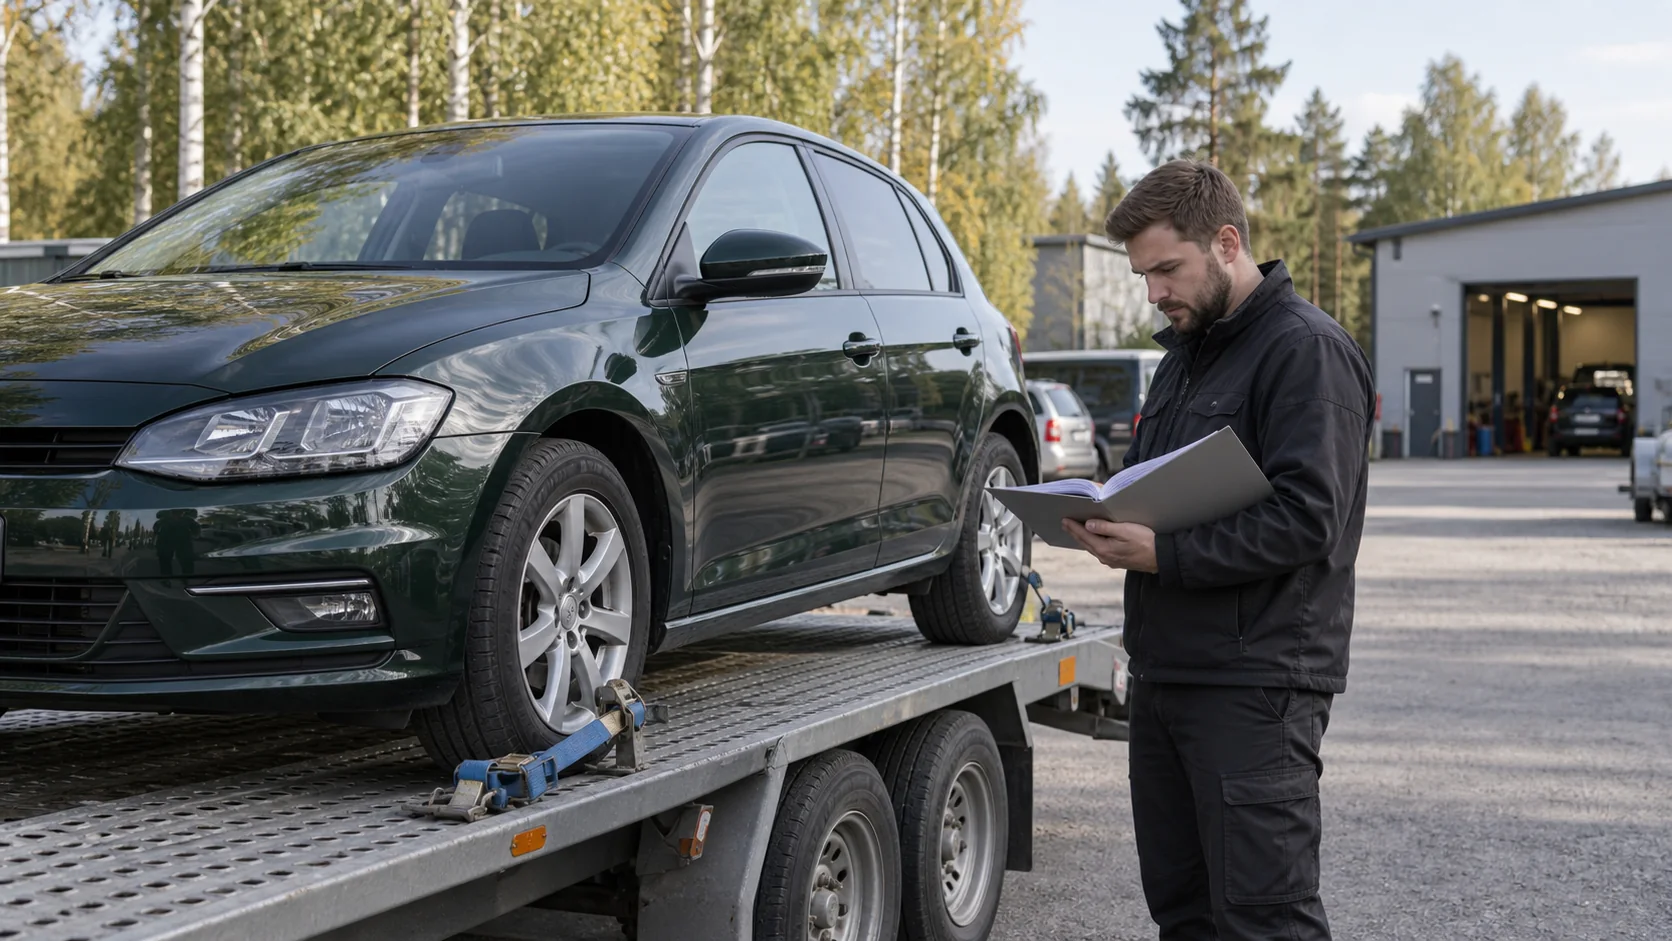
To transfer the car permanently, DGT indicates definitive deregistration for transfer to another country, which is necessary for subsequent registration in the destination country. Deregistration does not by itself authorise driving. While awaiting Italian plates, the two routes must be kept separate: Spanish green plates and driving the vehicle, or carriage on a vehicle transporter or another solution that does not put the car on the road on its own wheels. 6
| Option | Before departure | Decisive limitation |
|---|---|---|
| Green plates | Deregistration, ITV, plates and insurance | Check every State crossed 6, 8, 7 |
| Carriage on a vehicle transporter | Quote and documented delivery | Administrative obligations remain 6, 7 |
Spanish green plates for this branch are valid for 60 days. For a vehicle already registered in Spain, prior definitive deregistration for export and a valid ITV are required; if the car is driven, it must be insured. The H1 customs document cited by DGT concerns a non-EU destination and must not be added to this route to Italy. 8
A temporary plate valid in Spain does not automatically prove that it is recognised in Italy and the States crossed, nor that the individual policy covers the whole journey. Before collection, confirm in writing the permitted registered holder and driver, dates, documents to carry, recognition along the route and insurance cover. A vehicle transporter avoids road use of the vehicle’s plates, but does not remove tax, ownership and registration obligations. 9 7
Take care with residence too: for the owner of a foreign vehicle, the three months under Article 93-bis are linked to acquiring registered residence in Italy. A person who has long resided in Italy does not obtain three new months by buying the Spanish car today. REVE concerns specific availability arrangements or employment relationships and does not generally replace registration of a car bought into ownership. 9 10
Requirements and registration in Italy
For an intra-EU purchase by a private individual, the purchase data must be communicated within the 15 days following completion of the purchase and in any event before the registration application. The 15 days do not run from the car’s arrival in Italy. Therefore arrange the contract, documents and Italian contact before collection. 11 3
For an intra-EU private purchase meeting the conditions for exclusion from payment through F24 Elide, the Agenzia delle Entrate carries out prior document checks. A positive outcome from the Provincial Directorate is communicated to the CED and permits registration without that payment. This is a specific procedural branch, not a general VAT exemption, and it does not cancel the rules for vehicles new for VAT purposes. 3
In eligible EU/EEA cases, the STA may submit the unified application for UMC registration, entry in the PRA register and issue of the Documento Unico. If the application does not go through the STA, it proceeds first to the UMC and then to the PRA within 60 days of the date of the document preliminary to the DU. This time limit does not run from the contract or the vehicle’s arrival. 2
The ordinary technical check for registration in Italy is internal to the procedure: it does not require a separate application and has no standalone fee. Its positive result does not replace any tax condition. As a general rule, vehicles from other EU States are not subject to a prior technical examination and test (visita e prova), but DD 581 provides exceptions for certain approvals, damaged vehicles and other circumstances. Periodic roadworthiness inspection, administrative technical examination and test, and a pre-purchase inspection are different checks. 3
A budget without false totals
The financial comparison must include the price and VAT regime, any ITP, pre-purchase check, documents and translations, one transport option only, Motorizzazione, PRA and IPT, Italian plates, any technical procedures, repairs and the agency’s fee. The ACI source confirms only some PRA components: variable IPT, €27 in ACI fees and two €16 stamp duties. These three amounts are not the total cost of registration in Italy. Without quotes and vehicle data, no total should be calculated. 2
| Item | Amount | When to include it |
|---|---|---|
| Price and VAT | To be determined | Vehicle and seller 1 |
| ITP Form 620 | To be determined; 4% if applicable | Non-resident AEAT branch, not VAT 4 |
| Inspection | To be determined | Optional, before final payment 12, 13 |
| Documents and translations | To be determined | According to the file 3 |
| Green plates and policy | To be determined | Road driving only 8 |
| Carrier | To be determined | Alternative to driving 6 |
| Motorizzazione | To be determined | STA quote 3, 2 |
| ACI fees | €27 | PRA item, not a total 2 |
| Application stamp duty | €16 | PRA item 2 |
| DU stamp duty | €16 | PRA item 2 |
| IPT | To be determined | Vehicle and province 2 |
| Italian plates | To be determined | Actual application 2 |
| Technical procedures | To be determined | Only if required 3 |
| Repairs | To be determined | Actual condition 12, 5 |
| STA or agency | To be determined | If instructed 2 |
Operational checklist
| Check | Required outcome | Status |
|---|---|---|
| VIN and seller | Consistent with the originals 5, 3 | To check |
| Full DGT report | Restrictions, ITV and km checked 5 | To check |
| Precinto and reservation | Precinto cancelled; reservation cancelled or with the finance company’s express consent 6 | To check |
| Physical condition | Compared with the documents 5, 12 | To check |
| VAT and Form 620 | Branch established before final payment 1, 4 | To check |
| UMC/STA file | Originals and data confirmed 3, 2 | To check |
| Definitive deregistration | Completed; it does not authorise driving 6 | To check |
| Transport | One branch quoted 6, 8 | To check |
| Italian notification | Within 15 days and before registration 11, 3 | To check |
| STA or UMC–PRA | Sequence confirmed 2 | To check |
Documents or conditions still need checking. Do not treat the file as complete.
Frequently asked questions
When is it used for VAT purposes?
Only if it exceeds 6,000 km and six months from first registration. It is enough to remain within either threshold for it to be new for VAT purposes. 1, 2
Do Form 620 and the 4% rate apply to every purchase?
No. They concern the non-resident in the national AEAT branch and exclude VAT-taxable sales and buyers resident in Spain. If applicable: 4%, 30 working days from the contract, and a base not necessarily equal to the price. 4
Does the full DGT report replace a physical inspection?
No. It shows available data and restrictions, but does not prove authority to sell or current condition. Maintenance comes only from participating workshops: check the VIN, invoices and vehicle. 5
Can I drive in Italy with green plates?
In Spain they are valid for 60 days and require prior deregistration, valid ITV and insurance. However, check recognition and cover in Italy and every State crossed. 8, 7, 9
After purchase, do I have three months to drive with Spanish plates?
No, if you were already resident. The period runs from acquiring residence, not from the purchase; REVE does not generally replace registration of a car you own. 9, 10
Is the COC always compulsory, and must it be translated?
No. It is accepted in the original or as a copy without translation, and alternatives may exist. Non-harmonised certificates or certificates with annotations require the relevant translation. 3
Assess the car before committing
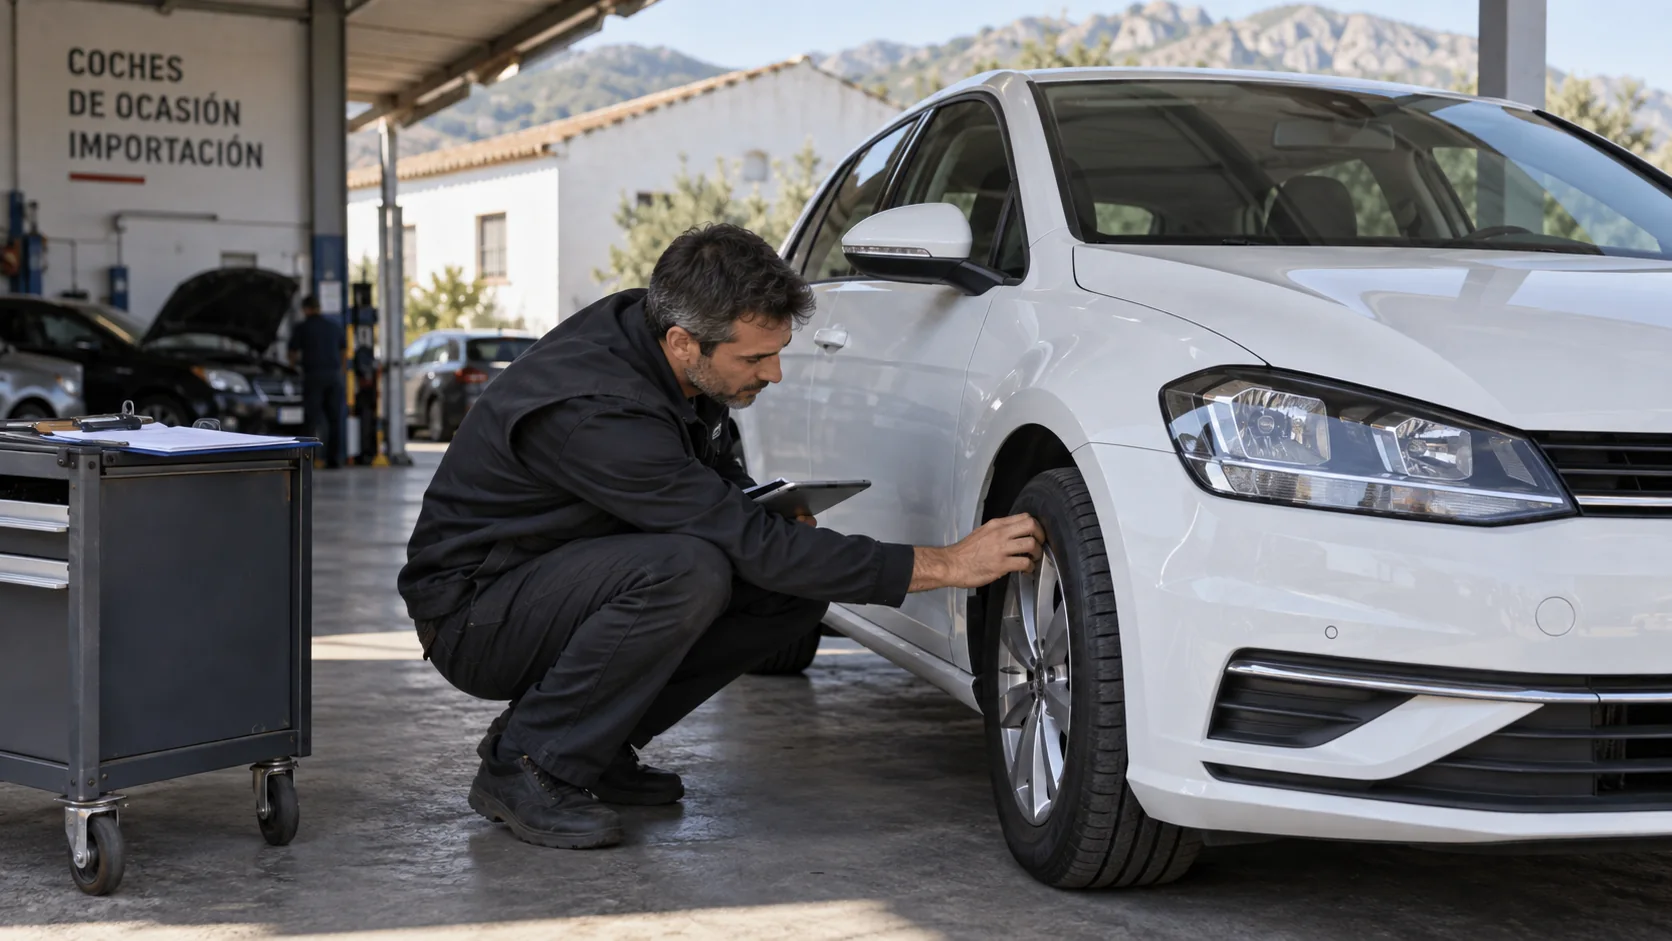
See the CarAudit inspection. The inspection does not include dismantling and depends on access and test conditions; it cannot guarantee detection of every fault or faults that emerge only later; the certificate is not a civil warranty. On 10 September 2026, Spain was outside public coverage: check availability and conditions, with no confirmed prices, dates or bookings. It does not promise transport, customs clearance or registration. 14, 12, 15, 13
Sources
- Your Europe — L'IVA quando compri o vendi un'automobile
- ACI Gov — Nazionalizzazione: iscrizione di veicolo usato proveniente dall’estero
- MIT — DD 581 del 17 dicembre 2025
- AEAT — Vehículos, embarcaciones de recreo y aeronaves usados, modelo 620
- DGT — Informe de un vehículo
- DGT — Baja definitiva por traslado del vehículo a otro país
- Your Europe — Car registration documents and formalities in the EU
- DGT — Matriculación temporal para particulares, placas verdes
- ACI Gov — Codice della strada, art. 93-bis
- ACI Gov — REVE: registrazione dei veicoli immatricolati all’estero
- Gazzetta Ufficiale — DM 26 marzo 2018
- CarAudit Italia — Cosa controlliamo
- CarAudit Italia — Cosa controlliamo
- CarAudit Italia — Home
- CarAudit Italia — Home and current coverage